Is your credit assessment process ready for CCD2?
EU banks have a limited window to test whether their credit processes are ready for 20 November 2026.
With only two months left until CCD2 applies, banks have a limited window to test whether their credit processes are ready for 20 November 2026.
CCD2 requires a thorough creditworthiness assessment based on relevant and accurate information. It also introduces requirements around automated assessments and a broader non-discrimination principle covering nationality and place of residence.
For credit teams, four areas deserve attention before November.
1. Do you know when the customer’s financial picture extends beyond your market?
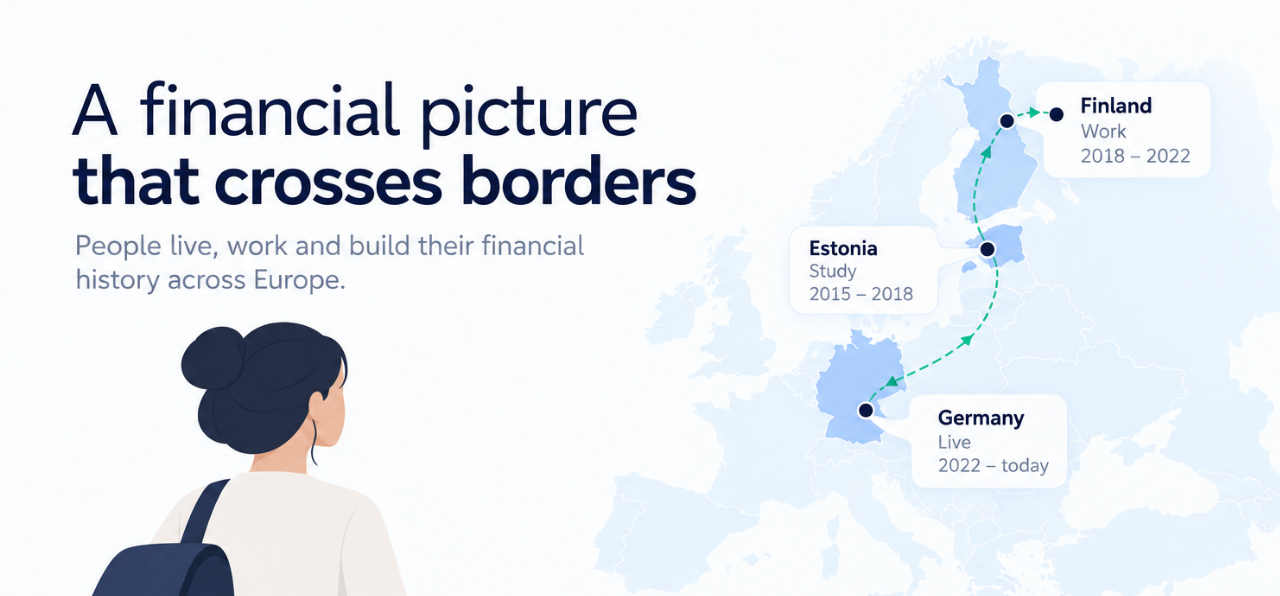
A customer applying for credit locally may have spent years living, working or borrowing elsewhere in Europe. Returning expats, EU mobile workers and foreign residents can all have financial commitments and credit histories across several countries.
Banks need a way to identify these cases during the application process. The consumer is the first source of information for the creditworthiness assessment, including information about financial commitments in other countries. Access to information held in foreign databases extends and completes the picture. The bank then needs to understand which of that information is relevant to the assessment and where verification may be needed.
Credit teams should review how multi-country financial histories are identified and which additional information may be relevant to the credit decision.
2. Can you get that information into the assessment?
Once a multi-country financial history is identified, the bank needs to assess the relevant information provided by the consumer and, where appropriate, verify its accuracy using reliable external sources, such as credit databases. Their use is particularly relevant concerning financial commitments or credit history in other markets. .
Verified information can give those processes greater confidence in the accuracy of the financial picture presented by the consumer.
The process should also define how unavailable information is handled. A missing data point should be recognised as an information gap rather than interpreted as evidence about the customer’s credit risk.
3. Can you explain and review the resulting decision?
CCD2 Article 18 gives consumers specific rights where automated processing of personal data is involved in creditworthiness assessment. These include the right to request human intervention and a clear and comprehensible explanation of the assessment.
Banks using automated scoring or decisioning should be able to show which information contributed to the assessment and support a human review when requested.
Testing this with actual lending workflows before November can reveal operational gaps that may not be visible from policies and documentation alone.
4. Are cross-border customers treated consistently?
Article 6 requires Member States to ensure that creditors do not discriminate against consumers on grounds of nationality or place of residence where they legally reside in the EU and apply for credit within the scope of the Directive.
A customer who recently moved to another EU country may have limited local credit history despite having years of relevant financial history elsewhere in Europe.
Credit teams should review how their processes handle these customers, particularly where domestic information is limited. This includes how information provided by the consumer is assessed and verified when financial commitments extend across borders.
Test the process before 20 November
Take a representative customer whose financial history spans two EU countries and run the application through the existing credit process.
Check how the bank identifies the relevant cross-border financial information provided by the customer, determines what needs to be verified, accesses reliable external sources, documents the assessment and supports explanation or human review where required.
This exercise can expose operational gaps while banks still have time to address them before 20 November.
Mifundo helps banks gain access and verify relevant financial information across borders by providing access to accurate credit and financial data from European markets. This information can be incorporated into existing credit processes while banks retain their own credit policies, models and lending decisions.
If access to financial information across borders remains a challenge in your CCD2 preparation, contact us to discuss your current process.